
GFN – NEW YORK: A light US data calendar between a softer-than-expected June jobs report and the 14 July consumer price index is unlikely to disturb market expectations for a prolonged Federal Reserve pause, analysts said.
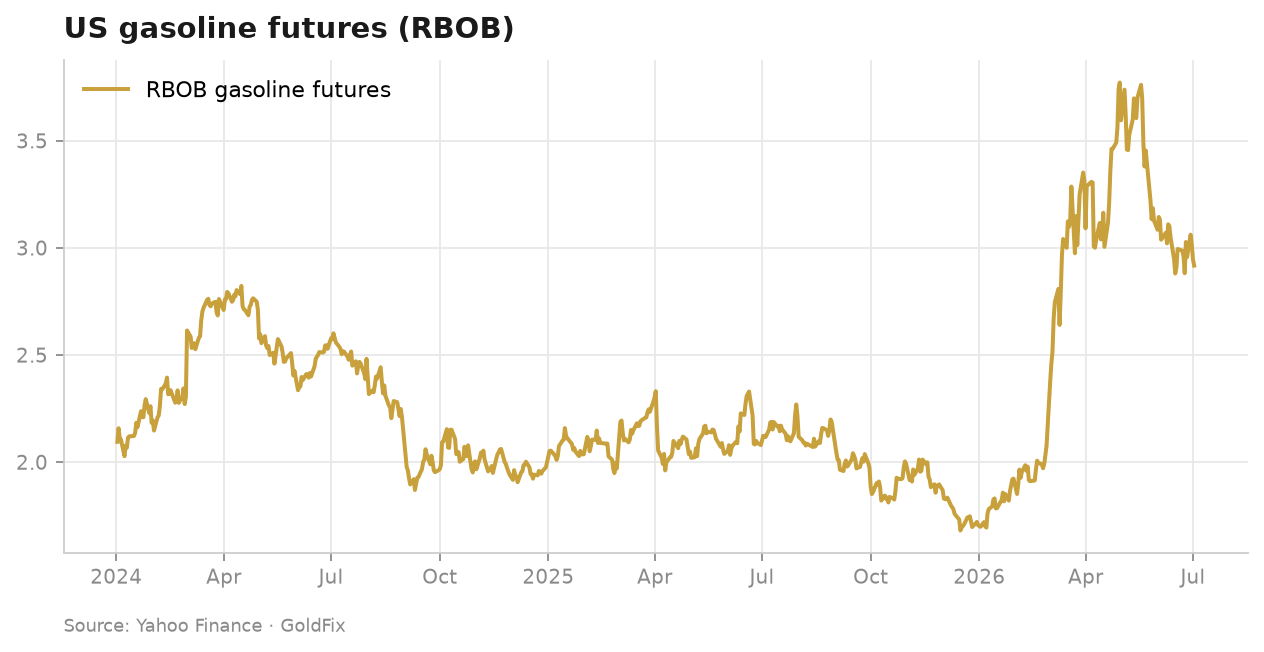
The June inflation reading is expected to show headline prices falling month-on-month, driven by a plunge in gasoline, a print that would reinforce market pricing for an extended hold and further diminish expectations of a rate increase later this year.
The intervening week offers little to challenge that view: the ISM services index is seen softening modestly while remaining consistent with GDP growth a little above 2%, the trade balance is set to deteriorate markedly on the basis of already-released advance goods figures, and existing home sales are expected to stay range-bound at weak levels as elevated prices and high mortgage rates continue to weigh on affordability.
"This may push the market further in the direction of anticipating a long pause from the Federal Reserve rather than an interest rate increase this year," the note said.
The same fuel-driven disinflation is evident across Central and Eastern Europe. In Poland, headline inflation returned to target in June, taking further rate hikes off the table and prompting speculation that the National Bank of Poland could eventually resume the rate cuts it suspended after the outbreak of conflict in the Middle East, though the assessment expects the bank to hold a wait-and-see stance while core inflation remains above 3%.
In the Czech Republic, June headline inflation is seen easing on weaker fuel prices and a marginally softer core, with retail sales and industrial output pointing to continued resilience despite headwinds tied to the Hormuz crisis.
The update adds to a broader picture of fuel-led disinflation running through developed and emerging European economies even as underlying core pressures hold above central-bank targets.